Money BetterThisWorld: A Modern Guide to Purposeful Wealth in 2026
Money betterthisworld isn’t a slogan. It’s a shift in how you think about cash, goals, and the life you actually want. This guide walks through purposeful wealth, step by step, in plain English. No jargon. No fluff. Just a practical financial strategy you can start today.
You’ve met someone who earns a lot and still feels broke. You’ve also met someone who earns less and sleeps fine at night. The gap isn’t the paycheck. It’s how each person handles money management. This article covers the full financial journey: awareness, budgeting, saving, debt, investing, income, and technology. By the end, you’ll have a real plan, not just a theory.
What Is Money BetterThisWorld?
Money betterthisworld means using money as a tool, not a trophy. It asks a simple question before every big decision: does this purchase, this job, this investment move me closer to the life I want? That’s the whole idea behind betterthisworld money thinking. It swaps “how much can I earn” for “what is this money actually for.”
This mindset doesn’t reject ambition. It just adds direction. Financial success stops being a number on a screen. It becomes a feeling of financial confidence and peace of mind. People who practice money better this world thinking often report less financial stress, even when their income stays the same. That’s the power of intentional wealth over blind accumulation.
Read More About: Mastering Supplement Management With TheSpoonAthletic: A Complete Guide to Smarter Health and Performance
Key Characteristics of Purposeful Wealth
Purposeful wealth looks different from traditional wealth-building. Traditional wealth chases bigger numbers. Purposeful wealth chases a better fit between money and life. The table below shows the contrast clearly.
| Traditional Wealth | Purposeful Wealth |
| Focused on wealth accumulation | Focused on intentional spending |
| Status-driven spending | Value-based spending |
| Chasing more income | Chasing meaningful outcomes |
| Short-term gratification | Long-term fulfillment |
| Financial success only | Financial well-being and personal success |
This comparison isn’t about judging anyone. It’s about noticing where your habits fall. Most people sit somewhere in the middle, and that’s completely normal. The goal is simply to move the needle toward money and values, one decision at a time.
Why Money BetterThisWorld Matters in 2026
Rising living costs aren’t slowing down. Rent, groceries, and healthcare have climbed faster than wages for years. That squeeze has pushed millions of Americans to rethink financial planning from the ground up. Economic uncertainty is no longer a rare event. It’s the background noise of daily life, and it demands a sharper financial strategy.
At the same time, financial technology has exploded. AI-powered financial tools, digital banking, and budgeting apps now put more control in your hands than ever before. That combination, tighter budgets plus better tools, is exactly why money better this world thinking is catching on fast. People want financial stability, not just a bigger paycheck that vanishes by the 20th of the month.
The Evolution of Wealth: From Accumulation to Purpose
The old formula was simple: work hard, earn more, buy more, repeat. It worked for a while. But it also quietly built a culture of consumer debt and lifestyle inflation. Many people followed this path and ended up with a great job and an empty savings account.
Purposeful wealth flips the script. It doesn’t reject earning or spending. It just asks that both serve a bigger picture. This shift matters more now than ever, because financial resilience depends on more than income. It depends on habits, patience, and a clear sense of future aspirations.
The New Wealth Formula
The new formula looks like this: earn, save, invest, align, impact. Each step feeds the next one. You earn to fund your life, save to build a cushion, invest to grow wealth over time, align spending with personal values, and use extra wealth to create positive impact.
This isn’t a rigid checklist. It’s a loop you repeat, year after year, as your income and goals change. Sustainable wealth comes from repeating small, smart actions, not from one lucky break.
The Five Core Principles of Money BetterThisWorld
These five principles form the backbone of purposeful wealth. Think of them as pillars. Remove one, and the whole structure gets shaky. Together, they turn money management from guesswork into a repeatable system.
Financial Awareness
Financial awareness starts with knowing where your money actually goes. Most people underestimate their own spending by hundreds of dollars a month, simply because they never track it. Expense tracking, even for one week, usually reveals at least one surprise leak.
You can’t build wealth creation on guesswork. Awareness means checking your bank app without flinching. It means knowing your monthly income, your fixed expenses, and your variable expenses by heart. This single habit often does more for financial progress than any fancy investment trick.
Financial Responsibility
Financial responsibility means owning your choices instead of blaming inflation, your boss, or bad luck. You can’t control the economy. You can control your spending habits, your bill payments, and how fast you pay down debt.
Small actions, repeated often, build real financial discipline. Paying a bill on time, skipping an impulse buy, moving cash into savings automatically, none of these feel exciting. But stacked over a year, they create noticeable positive financial outcomes.
Purpose-Driven Planning
Purpose-driven planning gives your money a job. Without a goal, income tends to leak away on things you barely remember buying. With a goal, every dollar has somewhere to go.
Maybe you’re saving for a house. Maybe you want to start a business or fund a degree. Whatever it is, naming it turns vague hope into a real plan. Financial goals work best when they’re specific: a number, a date, and a reason behind them.
Long-Term Wealth Growth
Long-term wealth growth rewards patience more than genius. Strategic investing works quietly in the background through compounding. A $10,000 investment earning 8% a year grows to roughly $46,600 after 20 years, without adding another cent.
| Starting Amount | Annual Return | Value After 20 Years |
| $10,000 | 8% | ~$46,600 |
| $25,000 | 8% | ~$116,500 |
| $50,000 | 8% | ~$233,000 |
Time in the market usually beats trying to time the market. This is one of the clearest lessons in all of personal finance.
Positive Impact
Once your own financial foundation feels solid, wealth can start doing more than paying your bills. It can fund a child’s tuition, support local businesses, or back charitable causes you believe in.
This is the “better this world” part of the philosophy. It’s optional, and it usually comes later in the journey. But for many people, using money to create meaningful impact feels more satisfying than any purchase ever did.
The Psychology of Money and Wealth
Money decisions rarely come from spreadsheets. They come from feelings. Understanding your own money habits matters just as much as understanding interest rates. Behavioral finance research consistently shows that emotion drives spending far more than logic does, especially under stress.
That’s why two people with identical salaries can end up in completely different financial places. One reacts to feelings. The other notices the feeling and pauses before spending. That pause is where financial wellness actually begins.
Emotional Spending
Emotional spending happens when a purchase soothes a feeling instead of meeting a need. Stress, boredom, anxiety, and even celebration can all trigger a shopping cart. None of this makes you weak. It makes you human.
The fix isn’t guilt. It’s awareness. Next time you feel the urge to buy something on impulse, pause for ten minutes. Ask yourself what feeling is driving the click. Often, the urge fades before you finish typing your card number.
Lifestyle Inflation
Lifestyle inflation creeps in quietly. A raise arrives, and suddenly the car gets nicer or the apartment gets bigger. Nothing wrong with enjoying success. But when every raise disappears into upgrades, wealth growth stalls completely.
A simple rule helps here: split every raise. Send half toward savings or investing, and keep the other half for lifestyle. This single habit protects your net worth without asking you to live like a monk.
Social Comparison
Social comparison has gotten louder thanks to social media. Everyone’s highlight reel looks perfect. Nobody posts their credit card statement or their student loan balance.
Comparing your real financial life to someone else’s curated feed is a losing game. Purposeful spending means measuring your progress against your own goals, not against a stranger’s vacation photos.
How Small Financial Decisions Create Long-Term Results
Imagine two people, Person A and Person B, earning the exact same salary. Person A spends every raise, carries a credit card balance, and saves whenever money happens to be left over. Person B invests every raise, keeps an emergency fund topped up, and resists lifestyle inflation.
“Wealth is what happens when small, boring decisions get repeated for ten years straight.”
After a decade, Person B typically ends up with a net worth several times higher than Person A, despite identical paychecks. This case study repeats itself constantly in real life. The lesson is simple: consistency beats intensity every single time.
How to Assess Your Current Financial Position
Before building anything new, take stock of where you stand. This step feels uncomfortable for many people, but it’s the foundation of every solid financial plan. You can’t set a useful destination without knowing your starting point.
Conduct a Personal Financial Audit
A personal financial audit means reviewing every part of your money picture at once. Look at your income, your fixed and variable expenses, your outstanding debt, your savings balances, and your investment accounts. Write the numbers down somewhere real, not just in your head.
This exercise usually takes less than an hour. Yet it often reveals patterns people never noticed, like a subscription they forgot about or a savings rate lower than they assumed.
Financial Metrics Worth Tracking
Certain numbers matter more than others. The table below highlights the ones worth checking every few months.
| Metric | Healthy Target |
| Savings rate | 20% or higher |
| Emergency fund | 3 to 6 months of expenses |
| Debt-to-income ratio | Below 36% |
| Investment contribution rate | Consistent monthly deposits |
| Net worth growth | Positive increase each year |
Tracking these financial metrics regularly turns vague worry into clear, actionable data.
How to Build a Purposeful Financial Plan
A plan turns wishes into steps. Without one, financial goals stay stuck as good intentions. A real plan connects today’s paycheck to tomorrow’s life.
Good planning doesn’t need to be complicated. It just needs to be honest, specific, and revisited often, since life changes and your plan should change with it.
Define Clear Financial Goals
Financial goals work best when they’re sorted by timeline. This keeps your financial planning organized and prevents short-term needs from swallowing long-term dreams.
Short-Term Goals
Short-term goals cover the next year or so. These usually include building emergency savings, paying off a credit card, or finally sticking to a working budget.
Medium-Term Goals
Medium-term goals stretch two to five years out. Common ones include buying property, launching a side business, or funding further education.
Long-Term Goals
Long-term goals look ten, twenty, or thirty years ahead. These often center on retirement planning, financial independence, or leaving something behind for family.
Align Spending With Your Values
Aligning money with priorities sounds abstract until you apply it to a single purchase. Before buying something, ask three quick questions: does this improve my life, does it support my goals, and will I still value it next month?
This filter cuts impulse spending fast. It doesn’t ban fun purchases. It just makes sure most of your money flows toward things that actually matter to you.
Budgeting Strategies That Work in 2026
No single budgeting method fits everyone. The right one depends on your personality and your income pattern. Smart budgeting simply means picking a system you’ll actually stick with.
Below are three proven approaches. Try one for a month before switching. Most people find their fit within the first two attempts.
Zero-Based Budgeting
Zero-based budgeting assigns every dollar a job before the month starts. Income minus expenses should equal zero, meaning nothing sits idle without a purpose.
Pay Yourself First
Pay yourself first flips the usual order. Instead of saving whatever’s left after spending, you move money into savings the moment your paycheck lands, then spend what remains.
Values-Based Budgeting
Values-based budgeting puts more money toward what matters most to you and less toward everything else. This method fits purposeful wealth thinking especially well, since it directly ties spending habits to personal values.
How to Save Money Without Sacrificing Quality of Life
Saving doesn’t require living on rice and beans. It requires optimizing, not eliminating. Regular saving works best when it feels sustainable, not punishing.
Small, repeated adjustments usually beat one dramatic cutback that burns out after three weeks.
Effective Saving Techniques
Automating transfers removes willpower from the equation entirely. Negotiating recurring bills, like phone or internet plans, often saves more than people expect. Cutting unused subscriptions and buying quality items that last longer both reduce waste without reducing joy.
Why Emergency Funds Matter
An emergency fund exists for the moments life throws a curveball: a job loss, a medical bill, a surprise car repair. Without one, these moments often turn into new debt.
A cushion covering three to six months of expenses gives real financial security. It turns a crisis into an inconvenience instead of a disaster.
Smart Debt Management Strategies
Debt isn’t automatically bad. It depends entirely on the type and the interest rate attached to it. Debt management starts with telling the two apart clearly.
Understanding Good Debt and Bad Debt
Good debt usually builds future value, like a mortgage, a business loan, or an education loan tied to real earning potential. Bad debt drains value instead, like high-interest debt on credit cards or payday loans.
Effective Debt Reduction Methods
Two popular debt reduction methods dominate this space. The snowball method pays off the smallest balance first for quick motivation. The avalanche method targets the highest interest rate first to minimize total cost.
| Method | Best For |
| Snowball | Motivation and quick wins |
| Avalanche | Minimizing total interest |
| Hybrid | A balance of both approaches |
Paying down high-interest debt often delivers a better guaranteed return than most investments ever could.
Investing for Purposeful Wealth
Inflation quietly erodes cash sitting in a low-interest account. Strategic investing protects and grows your purchasing power over time, making it a core piece of any serious wealth-building strategy.
Investing doesn’t require expert-level knowledge to start. It requires consistency, patience, and a basic understanding of your options.
Major Investment Categories
Four main categories make up most diversified investments. Each behaves differently, and together they help balance an investment portfolio.
Stocks
Stocks give you partial ownership in a company. They carry higher risk but historically offer strong long-term growth.
Bonds
Bonds function more like a loan to a government or company. They typically offer steadier, lower-risk income.
Real Estate
Real estate can generate rental income and long-term appreciation, though it usually requires more upfront capital and hands-on management.
ETFs
ETFs bundle many stocks or bonds into a single investment, offering instant diversification without needing to pick individual winners.
Common Investing Mistakes
Common investing mistakes include panic selling during downturns, trying to time the market perfectly, ignoring fees that quietly eat returns, and chasing whatever trend is loudest online. Patience almost always beats cleverness in investment decisions.
Read More About: Newstown CraigScott Capital: Full Background, Regulatory History, Risks, and Investor Guide 2026
Modern Income Strategies for 2026
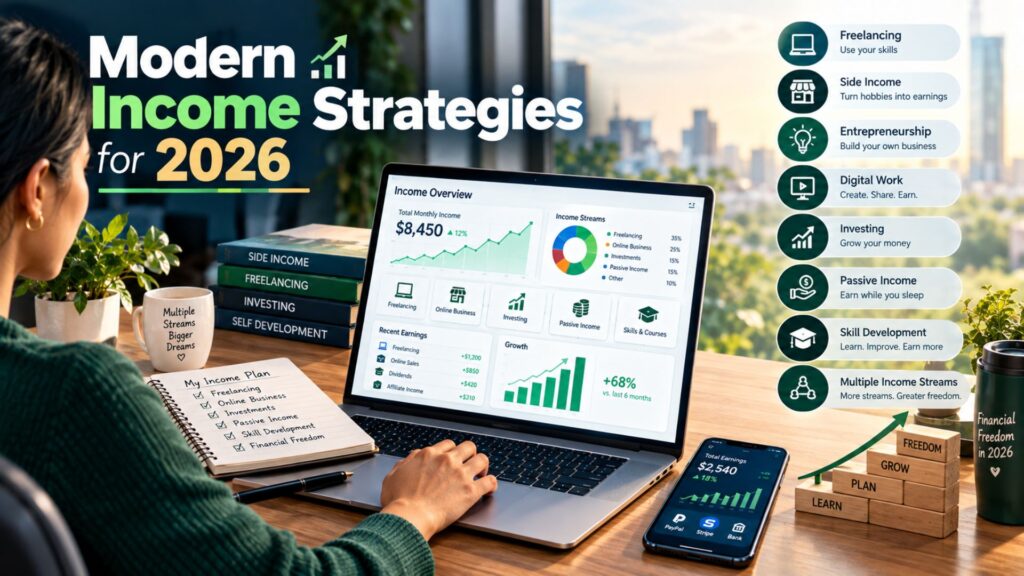
Income doesn’t have to come from one place anymore. Multiple income streams give people more stability and more room to invest toward their goals.
Technology has made building these streams far more accessible than it was even five years ago.
Increasing Your Primary Income
Boosting your main paycheck often comes down to skill development, earning professional certifications, sharpening leadership ability, and improving negotiation skills during reviews or job changes.
Building Additional Income Streams
Popular options for extra income include freelancing, consulting, affiliate marketing, online education, and content creation. Each requires effort upfront but can grow into a meaningful second income over time.
Understanding the Reality of Passive Income
Passive income rarely starts passive. Most streams demand serious effort before they run on autopilot. Setting realistic expectations here prevents disappointment and keeps motivation intact.
Technology and Modern Money Management
Financial technology has reshaped how people manage money day to day. Tools that once required a financial advisor now sit in everyone’s pocket.
This shift has made financial education and hands-on management far more accessible to the average person.
AI-Powered Financial Tools
AI-powered financial tools now track spending automatically, spot unusual patterns, and even suggest where to cut back. Some apps forecast your balance weeks in advance based on your habits.
Digital Banking Advantages
Digital banking typically offers lower fees, faster transfers, and clearer insight into spending than traditional brick-and-mortar banks ever provided.
Financial Cybersecurity
Protecting your money online matters as much as growing it. Strong passwords, multi-factor authentication, and regular account monitoring all guard against cybersecurity threats targeting personal finances.
Purposeful Wealth and Life Satisfaction
Research consistently shows money boosts happiness, but only up to a point. Beyond covering basic needs and reducing daily stress, extra income adds less and less to overall life satisfaction.
Purposeful wealth focuses on freedom, security, relationships, and personal growth instead of endless accumulation. These factors tend to matter more for financial well-being than any number in a bank account.
How to Use Wealth to Create Positive Impact
Money, once it covers your own needs, can become a genuine force for good. This is where positive impact and financial responsibility meet, turning personal success into something bigger.
Practical Ways to Create Financial Impact
Supporting charitable causes, investing in local businesses, mentoring new entrepreneurs, and creating jobs through a small business all count as real, tangible financial impact.
Common Myths About Money BetterThisWorld
Several myths quietly hold people back from purposeful wealth. The table below clears up the most common ones.
| Myth | Reality |
| More income guarantees wealth | Spending habits matter more than income size |
| Budgeting restricts freedom | Budgeting actually creates financial freedom |
| Investing is only for the rich | Anyone can start with small, consistent amounts |
| Financial success happens quickly | Real wealth accumulation takes sustained time |
| Multiple income streams guarantee success | Execution matters more than the number of streams |
Financial Mistakes That Can Prevent Long-Term Growth
Most setbacks trace back to a handful of avoidable habits rather than bad luck. Recognizing these patterns early protects years of future progress.
Common Money Management Mistakes
Living without clear financial goals, ignoring investing entirely, overspending after every raise, carrying high-interest debt for years, skipping an emergency fund, and making decisions from emotion instead of a plan all quietly block financial growth.
A 30-Day Money BetterThisWorld Action Plan
Big change rarely starts big. It starts with thirty focused days. This plan breaks the financial journey into manageable weekly stages.
Days 1–7: Build Financial Awareness
Track every expense, calculate your current net worth, and review every subscription you’re paying for.
Days 8–14: Gain Financial Control
Build a working budget, cut unnecessary spending, and automate your savings transfers.
Days 15–21: Focus on Growth
Open an investment account if you don’t have one, research diversified investments, and set a realistic monthly contribution target.
Days 22–30: Optimize Your Strategy
Review what worked, adjust what didn’t, and sketch a rough twelve-month roadmap based on your first month’s data.
The Future of Money BetterThisWorld
The next phase of personal finance will lean heavily on personalization and automation. Expect more AI financial tools, automated wealth management, and highly personalized financial strategies built around individual goals rather than generic advice.
People who blend smart technology with a clear growth mindset will likely see the biggest gains. The tools keep getting better, but the underlying principles of financial discipline stay exactly the same.
Frequently Asked Questions
What does Money BetterThisWorld mean?
It’s a philosophy that treats money as a tool, aligning financial decisions with personal values and long-term goals instead of chasing income for its own sake.
Is purposeful wealth different from financial independence?
Yes. Financial independence means work becomes optional. Purposeful wealth is broader, shaping how you use money at every income level, whether or not independence is even the goal.
How much should I save every month?
Many experts suggest around 20% of income, though the right number depends on your expenses, your financial goals, and your personal timeline.
Can beginners start investing with small amounts?
Absolutely. Many platforms allow starting contributions as low as five or ten dollars, letting compounding do the heavy lifting over time.
Why is purposeful wealth becoming popular?
People increasingly want financial stability and genuine life satisfaction, not just endless consumption driven by comparison and status.
Conclusion
Money betterthisworld isn’t about getting rich overnight. It’s about building a financial foundation that actually supports the life you want. Financial awareness, smart budgeting, strategic investing, and honest debt management all work together toward one goal: real financial freedom.
Start small. Track one week of spending. Automate one transfer. Open one investment account. Purposeful wealth grows from decisions like these, repeated steadily over time, until one day you look up and realize money finally works for you instead of the other way around.
2 Comments