Newstown CraigScott Capital: Full Background, Regulatory History, Risks, and Investor Guide 2026
If you are Investors searching for Newstown CraigScott Capital, you may find a mix of historical pages, financial discussions, regulatory records, and outdated references. The name can be confusing because Newstown CraigScott Capital is not the same thing as a current registration record. The documented historical entity that appears in U.S. regulatory records is Craig Scott Capital, LLC, a former brokerage firm with FINRA CRD number 155924. FINRA’s current BrokerCheck report states that the firm is no longer registered and records its registration from January 20, 2012, through September 7, 2017.
This guide explains the Newstown CraigScott Capital history, the documented regulatory record, the SEC action involving Craig Scott Capital, and the practical lessons for U.S. retail investors. It also explains how to conduct investor due diligence before trusting a financial firm. The goal is not to rely on online rumors. It is to understand the public records, identify the correct legal identity, and learn how regulatory oversight can help investors make informed decisions.
Read More About: Hosted Event PBLGamevent: How Gaming Events Are Organized in 2026
What Is Newstown CraigScott Capital?
Newstown CraigScott Capital is a search phrase that appears to be associated online with historical information about CraigScott Capital, particularly the former brokerage firm known legally as Craig Scott Capital, LLC. The supplied source describes the phrase as appearing in discussions involving archived content, regulatory references, investor forums, and educational material.
The important point is that investors should not assume that an online name automatically represents a currently operating brokerage firm. FINRA’s current record identifies the legal entity as Craig Scott Capital, LLC, CRD #155924. It also states that the firm is no longer registered with FINRA or a national securities exchange. Therefore, anyone researching Newstown CraigScott Capital should first determine exactly which company the search result refers to.
Newstown CraigScott Capital vs. Craig Scott Capital, LLC
The distinction between a search phrase and a verified legal entity is important in financial firm research. A website, social-media account, directory, or article may use a name that looks similar to a regulated company. That does not establish that the website is operated by the same organization.
FINRA’s record provides several identifiers for Craig Scott Capital, LLC, including its CRD number, SEC number, historical address, business structure, and registration information. These identifiers are more useful than a name alone when checking a firm’s legal identity.
Newstown CraigScott Capital History: Key Facts
The Newstown CraigScott Capital history is best understood through the documented history of Craig Scott Capital, LLC. FINRA’s BrokerCheck report identifies the company as a New York limited liability company formed on October 13, 2010. Its CRD number was 155924 and its SEC number was 8-68751. The report lists Uniondale, New York, as its main office location.
The firm became a broker-dealer registered with the SEC in January 2012. The SEC’s 2016 administrative order states that the firm generated revenue primarily through commission income from retail customer accounts. FINRA records that its registration ran from January 20, 2012, to September 7, 2017. FINRA also records that the firm ceased doing business on December 31, 2015. (SEC)
| Fact | Documented information |
| Legal name | Craig Scott Capital, LLC |
| CRD number | 155924 |
| SEC number | 8-68751 |
| Business structure | New York limited liability company |
| Formation date | October 13, 2010 |
| Broker-dealer registration | January 20, 2012 |
| Registration ended | September 7, 2017 |
| FINRA status | No longer registered |
| Historical headquarters | Uniondale, New York |
| Historical revenue model | Primarily commission income from retail customer accounts |
These facts help separate the documented brokerage history from later online references using the term Newstown CraigScott Capital.
Regulatory History of CraigScott Capital
The most important part of the documented history concerns regulatory oversight. In April 2016, the SEC issued an administrative order involving Craig Scott Capital, LLC, Craig S. Taddonio, and Brent M. Porges. The proceeding was Release No. 34-77595 and File No. 3-17206. (SEC)
The SEC order concerned customer-information safeguards and business-record preservation. The SEC found that the firm had failed to adopt written policies and procedures reasonably designed to protect the security and confidentiality of customer records. It also found violations involving the making and keeping of certain business communications. The order states that more than 4,000 customer and third-party faxes were received through non-firm email addresses during the relevant period, and that employees and principals also used personal email for firm business. (SEC)
What the SEC Found
The SEC order says the relevant conduct ran from January 20, 2012, until approximately June 2014. Customer information transmitted through the electronic fax system included names, addresses, Social Security numbers, bank and brokerage account numbers, identification documents, and other financial information. The SEC also found that certain business emails sent or received through personal accounts were not maintained and preserved as required. (SEC)
The order states that the firm’s written supervisory procedures were not reasonably designed to protect customer information. It says the procedures did not properly address the electronic fax system, contained incomplete sections, and did not adequately reflect the firm’s actual practices. (SEC)
SEC Regulatory Sanctions
The SEC ordered Craig Scott Capital to cease and desist from the relevant violations. The firm was censured and ordered to pay a $100,000 civil money penalty. The two individual respondents named in the order were also subject to separate sanctions. (SEC)
An important legal detail is that the SEC order states that the respondents submitted offers of settlement and consented to the order without admitting or denying the findings, except for jurisdiction and matters specifically stated in the order. That distinction matters when discussing regulatory actions because a regulatory settlement should be described according to the wording and legal status of the actual order. (SEC)
What FINRA BrokerCheck Shows
FINRA BrokerCheck is one of the most useful tools for U.S. brokerage due diligence. FINRA describes BrokerCheck as a free resource for researching financial advisers and firms. It provides information about registration, licensing, employment history, regulatory actions, complaints, arbitrations, and other disclosures. (BrokerCheck)
The current BrokerCheck report for Craig Scott Capital, LLC identifies ten regulatory events and six arbitration disclosures. It also states that the firm is no longer registered with FINRA or a national securities exchange.
| BrokerCheck information | Craig Scott Capital, LLC |
| Regulatory events | 10 |
| Arbitration disclosures | 6 |
| Current FINRA registration | No |
| Historical CRD | 155924 |
| Registration period | 01/20/2012–09/07/2017 |
| Firm ceased business | 12/31/2015 |
These records should be interpreted carefully. FINRA explains that BrokerCheck can contain allegations, pending matters, settlements, and other disclosure events. A disclosure is not automatically proof that every allegation was established. Investors should read the individual event and its final disposition rather than relying only on a headline or event count.
Understanding the Brokerage Business and Investor Risks
A boutique brokerage firm is generally smaller than a major national financial institution. Such firms may offer more direct advisor relationships and a more personal customer relationship. The supplied article notes that boutique firms can focus on personalized services while operating with fewer resources than large institutions.
A historical brokerage firm can earn money through trading commissions, advisory fees, asset management fees, product sales, and other services. The compensation structure matters because different payment methods can create different conflicts of interest. A commission-based model, for example, can connect revenue to transactions. That does not by itself establish misconduct, but it makes fee transparency and understanding incentives important parts of investor research.
| Cost or incentive | What investors should understand |
| Trading commissions | Costs connected with buying or selling securities |
| Advisory fees | Fees paid for investment or planning services |
| Asset management fees | Ongoing charges for managing assets |
| Hidden fees | Costs that may be less obvious without reviewing documents |
| Compensation structure | How the adviser or firm earns revenue |
| Product-related compensation | Payments or incentives linked to certain products |
Investors should also consider market volatility, investment costs, taxes, liquidity, and their own risk tolerance. A low-cost investment can still lose money. A high-cost investment can also perform well in a particular period. The point of brokerage accountability is not to eliminate market risk. It is to make sure investors understand what they are paying for and what risks they are taking.
Common Brokerage Risks Investors Should Understand
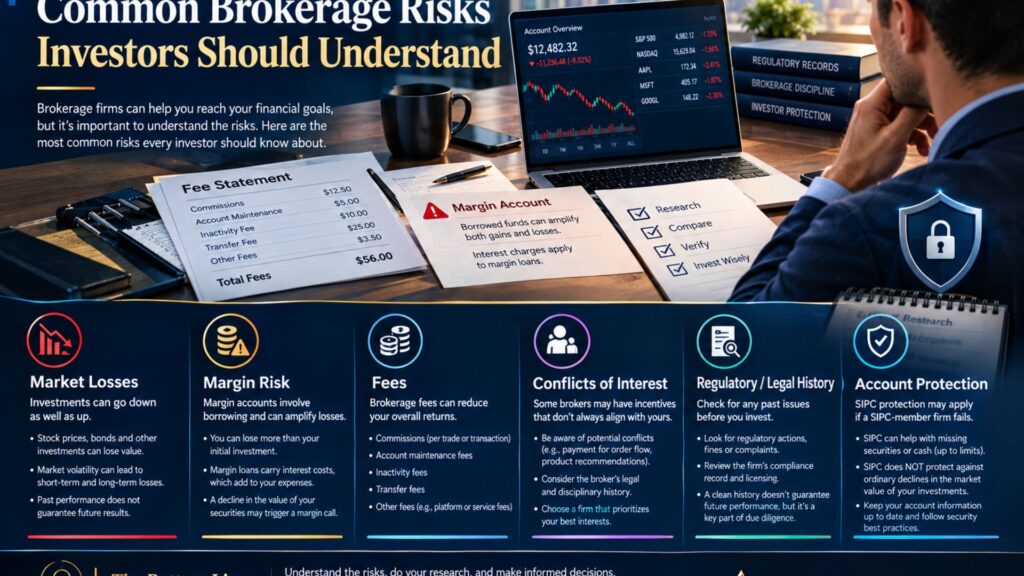
Some terms commonly appear when researching brokerage complaints and regulatory concerns. These include excessive trading, churning, unauthorized trading, unsuitable recommendations, and misrepresentation. These are important concepts, but they should not automatically be attributed to a particular firm unless supported by a specific regulatory or legal record.
Excessive trading generally refers to trading activity that may be inconsistent with a customer’s interests or objectives. Churning is a more specific concept involving excessive transactions in a customer’s account to generate compensation. High account turnover and large commission expenses can be warning signs that deserve closer examination.
Unauthorized trading refers to transactions made without the required customer authorization. Unsuitable recommendations concern recommendations that may not fit a customer’s circumstances, investment objectives, risk tolerance, or time horizon. Misrepresentation involves inaccurate or misleading information about an investment, service, fee, risk, or other important matter.
The applicable legal and regulatory standards can vary by situation. Investors should distinguish the suitability standard from a fiduciary standard and should understand what duties apply to the professional and service involved. A fiduciary relationship can impose broader duties than a suitability obligation.
Why Customer Records and Compliance Matter
The Craig Scott Capital SEC action provides an important example of why compliance is not simply paperwork. The SEC found that the firm lacked adequate procedures for protecting customer information and preserving certain business communications. The order described the use of non-firm email accounts and an electronic fax system that routed sensitive information through non-firm addresses. (SEC)
For modern investors, the lesson extends to digital operational protocols. A financial firm needs systems for secure communication, recordkeeping, access controls, encryption, data retention, employee supervision, and customer-information protection. These areas are part of the broader securities industry framework and support retail investor protection.
“Verify before you trust.”
This simple principle also fits modern financial security. Investors should not only ask whether a firm has an attractive website. They should ask how the business handles customer data, account records, trade confirmations, account statements, and ongoing account monitoring.
Newstown CraigScott Capital and Name Confusion Risks
Search engines can create confusion when an old company name appears beside a newer business name. A historical financial firm may have pages that remain online long after its business activity has ended. Third-party reviews may also copy information from older sources without updating it.
That is why legal identity is critical. When researching Newstown CraigScott Capital, compare the name against the firm’s CRD number, SEC registration information, state records, historical addresses, ownership information, and other legal filings. FINRA’s report identifies Craig Scott Capital, LLC as CRD 155924 and records its historical Uniondale, New York address.
A practical identity check should include these records:
| Verification item | Why it matters |
| Legal name | Confirms the actual entity |
| CRD number | Distinguishes firms with similar names |
| SEC number | Provides another regulatory identifier |
| Registration status | Shows whether the firm is currently registered |
| State records | Provides additional jurisdictional information |
| Form BD | Helps document broker-dealer registration information |
| Ownership | Helps identify controlling interests |
| Business address | Helps identify the actual firm |
Is Newstown CraigScott Capital Legitimate?
The word “legitimate” needs careful treatment in financial research. A firm may have existed legally in the past but no longer operate today. A historical registration does not establish current authorization. Likewise, the existence of an online page does not establish that a company is currently registered.
For the documented Craig Scott Capital, LLC entity, FINRA’s current report says the firm is no longer registered and gives its historical registration period as January 20, 2012, through September 7, 2017. The same report states that the firm ceased doing business on December 31, 2015.
Therefore, an investor encountering the name in 2026 should verify the exact entity rather than assuming that a current website, advertisement, or social-media profile represents the historical firm.
How to Research a Brokerage Firm Before Investing
Effective investor due diligence starts with identity verification. Search the firm’s exact name in FINRA BrokerCheck. Review the registration status. Then examine the firm’s regulatory record, disciplinary history, investor complaints, and arbitration information where available. FINRA explains that BrokerCheck draws information from the Central Registration Depository and includes information supplied by firms and regulators.
The next step is to examine the firm’s legal documents and business structure. Investors can consider checking Form BD, state securities records, SEC databases, ownership information, and relevant legal filings. They should also review the firm’s clearing services and custody arrangements. FINRA’s historical report for Craig Scott Capital states that the firm did not itself hold or maintain funds or securities or provide clearing services for other broker-dealers, and identifies COR Clearing LLC as a third-party arrangement for customer accounts, funds, securities, and records.
The process can be summarized as:
Firm name → Legal identity → Broker registration → Regulatory records → Disclosures → Fees → Custody arrangements → Investment suitability → Ongoing account monitoring
This process helps reduce financial risk mitigation problems caused by incomplete research.
Investor Due Diligence: What to Check
Before opening an account, investors should verify registration and licensing status. They should confirm the firm’s exact legal name and review its disclosure history. They should also ask for a complete explanation of fees and compensation.
Before buying an investment, investors should compare the product with their investment goals, risk tolerance, and investment horizon. They should understand liquidity restrictions, market risks, fees, and possible capital erosion. If the investment is difficult to explain in simple terms, the investor should request clearer documentation.
Before transferring assets, investors should confirm who actually holds the money or securities. They should verify transfer instructions independently. They should not assume that a person contacting them through email, social media, or a messaging app is authorized to represent a regulated company.
Traditional Brokerage Models and Modern Wealth Management
The brokerage industry has changed significantly. Traditional commission-based brokerage often relied heavily on transaction-related compensation. Modern wealth management can include fee-based advisory services, digital investment platforms, automated portfolio management, and fiduciary planning.
Neither model should be judged only by its label. Investors should examine the actual costs, services, conflicts, investment process, and regulatory obligations involved. A fee-based service can still have expenses. A commission-based service can still provide legitimate services. The important issue is whether the investor understands the arrangement.
| Area | Traditional brokerage model | Modern wealth management |
| Compensation | Often transaction-related | Often fee-based |
| Advisor contact | Often direct | Direct, digital, or combined |
| Technology | Historically more limited | Often highly digital |
| Portfolio tools | Advisor-led | Advisor, software, or both |
| Fee disclosure | Varies by firm | Often presented through detailed schedules |
| Planning | May focus on transactions | May include broader financial planning |
Modern systems may also use algorithmic execution, digital alerts, portfolio analysis, and automated rebalancing. These tools can improve monitoring, but investors still need to understand how decisions are made.
Investor Protection Resources for 2026
For U.S. investors, FINRA and the SEC provide important sources of official information. FINRA’s BrokerCheck can help investors research brokers and brokerage firms. The SEC provides enforcement records and investment-adviser information. State securities regulators can provide additional information at the state level. FINRA itself recommends using BrokerCheck and state regulators when researching financial professionals. (BrokerCheck)
Investors should treat official public regulatory database information as a starting point rather than the only source. Third-party reviews may provide context, while regulatory records provide documented regulatory information. The two should not be treated as equivalent.
Red Flags in Brokerage and Investment Offers
Certain warning signs deserve additional research. Guaranteed high returns should be treated cautiously because investment returns normally involve risk. Pressure to send money quickly can also make it harder to perform proper investment research.
Unclear fees are another warning sign. Investors should request written fee disclosure before committing money. Licensing problems, inconsistent company names, unexplained changes in ownership, unusual payment instructions, and unsolicited investment opportunities also deserve careful verification.
Technology creates additional risks. Modern scams can imitate legitimate companies, use copied logos, reproduce regulatory language, or link to fake versions of FINRA BrokerCheck. FINRA specifically warns investors about imposters and fraudulent websites that may misuse the BrokerCheck name.
Read More About: Highlights of Nummazaki: Scenic Coastal Attractions and Travel Guide 2026
Lessons From the Craig Scott Capital Regulatory Record
The historical record provides several practical lessons. First, regulatory compliance matters because financial firms handle sensitive customer information and securities transactions. Second, transparency matters because investors need clear information about registration, costs, risks, and business relationships.
Third, investors should understand that regulatory records can involve different types of proceedings. A regulatory action, customer arbitration, civil case, and unresolved allegation are not necessarily the same thing. FINRA explains that BrokerCheck disclosure events can have different statuses, including pending, appealed, and final dispositions.
The Craig Scott Capital SEC proceeding is a particularly clear example of why primary documents matter. The SEC order identifies the specific rules involved, describes the conduct, states the findings, and lists the sanctions. (SEC) That is more informative than relying on a short online statement that simply says a firm had “regulatory problems.”
Frequently Asked Questions
Why do investors still search for Newstown CraigScott Capital in 2026?
Historical brokerage records can remain searchable for years. The supplied article notes that searches may arise from archived material, regulatory discussions, investor research, and older online references.
What is Craig Scott Capital, LLC?
Craig Scott Capital, LLC was a New York limited liability company and historical broker-dealer. FINRA identifies it by CRD number 155924 and states that it is no longer registered.
What was Craig Scott Capital’s FINRA CRD number?
The firm’s FINRA CRD number was 155924. Its SEC number was 8-68751.
What happened to Craig Scott Capital?
FINRA’s current BrokerCheck record says the firm ceased doing business on December 31, 2015, while its registration record runs through September 7, 2017. The record therefore needs to be read carefully rather than reduced to a single date.
What regulatory action involved Craig Scott Capital?
In April 2016, the SEC issued an administrative order involving Craig Scott Capital, LLC and two individuals. The SEC found violations involving customer-information safeguards and recordkeeping. The firm was censured and ordered to pay a $100,000 civil penalty. (SEC)
Did the SEC action concern excessive trading?
The specific SEC order examined here concerned customer-information safeguards and recordkeeping. It did not establish the excessive trading or churning allegations discussed generally in this guide. Investors should not combine unrelated brokerage-risk concepts with a specific regulatory case without evidence.
Why are regulatory records important?
Regulatory records provide documented information about registration, disclosures, enforcement actions, and other regulatory matters. They can help investors distinguish historical facts from online opinions.
Can online reviews replace regulatory research?
No single source should replace proper research. Reviews can provide experiences or opinions, but official records are important for checking registration, regulatory actions, disciplinary history, and other disclosed events.
How can I verify a U.S. brokerage firm?
Start with FINRA BrokerCheck. Confirm the exact legal name and registration status. Then review regulatory records, state records, SEC information where applicable, and the firm’s disclosures. Also examine fees, custody, clearing arrangements, and the investment itself.
What should investors check before transferring assets?
Investors should confirm the recipient’s legal identity, registration status, account details, custody arrangements, and transfer instructions. They should independently verify payment instructions before sending funds.
Conclusion
The phrase Newstown CraigScott Capital should be researched carefully because the documented regulatory entity is Craig Scott Capital, LLC, a historical brokerage firm identified by FINRA as CRD 155924. FINRA’s current report states that the firm is no longer registered and records its registration from January 20, 2012, through September 7, 2017.
For investors, the broader lesson is practical. Do not rely on a name alone. Verify the legal identity, broker registration, licensing status, regulatory record, disclosure history, fees, custody arrangements, and investment risks. Use FINRA BrokerCheck, SEC
In 2026, historical financial information can remain online long after a firm has stopped operating. That makes careful financial firm research, accurate identification, and independent verification especially important when researching Newstown CraigScott Capital, CraigScott Capital, or any other historical investment brokerage.


One Comment